Are traders wrong about Alphabet’s potential upside in October?
Polymarket traders think Alphabet has a 30% chance of hitting $380, and I think those odds present a huge market opportunity.


Alphabet shares are up just under 10% this year, trading at around $346 on Thursday. This makes it one of the worst performers among the big technology companies that have made significant investments in AI.
Meta Platforms, Alphabet’s closest peer, is also up just over 10%, while the likes of Advanced Micro Devices and Micron Technology have more than doubled in price this year.
Alphabet has been one of the biggest investors in AI this year, with its capex forecast around $200 billion in 2026. However, investors remain skeptical as to whether such investments will pay off, explaining why the stock price is underperforming the S&P 500 Index.
This perhaps explains why Polymarket traders are not overly optimistic about Alphabet’s potential gains in October, with a $370 price target given just a 46% chance, while $380 is at 30%.
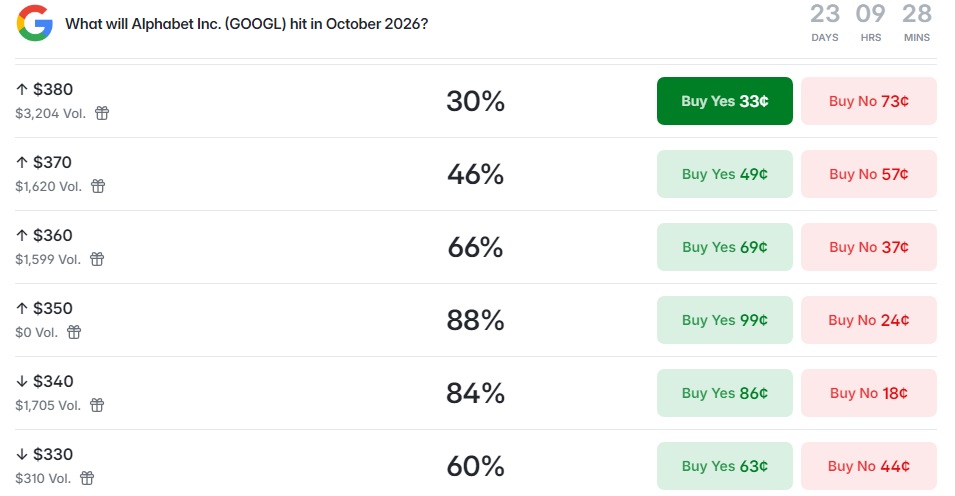
A yes bet on the $370 price target is currently trading at $0.49 per share on Polymarket, while the $380 price target is going for $0.33. I think the $380 price target is an opportunity, especially heading into the company’s Q3 earnings later in October.
Are traders undervaluing Alphabet’s potential in October?
Alphabet has already witnessed two significant post-earnings rallies this year, with the stock spiking 14% after Q1 earnings in April and 17% after Q2 earnings in July. Can it pull out another one after Q3?
History says it can. Alphabet has outperformed consensus analyst expectations on earnings in each of the last eight quarters, so it is highly likely that it will repeat the feat again when Q3 earnings are out on October 28.
Often when companies beat earnings, the stock price reacts positively, especially if those results are accompanied by positive guidance. However, for companies investing in AI, investors are looking at more than just an earnings beat. They want to see how the company is repaying them for those huge investments in artificial intelligence. So a lot of attention will be directed towards ROI.
When the company raised its capex forecast for 2026, it said it was in response to rising demand for Google Cloud Services and the Gemini AI ecosystem. So, you could say this spending is necessitated by the market, and not the company spending and hoping to capture a significant share of the market.
Moreover, the company’s revenue for Q2 surged more than 24% year-over-year to $119 billion, driven by the integration of AI into its core segments, Cloud and Services.
Therefore, given the rate at which pure-play AI companies have demonstrated since June, with the likes of Anthropic and OpenAI’s annual revenue run-rates approaching $70 billion, Alphabet should be looking at adding to its Q2 numbers in the upcoming quarter, which should trigger a positive response from investors. A 10% spike in the stock price, based on the current price of about $346, would take it closer to $380.
This page does not constitute investing advice. Prediction markets and/or gambling may result in loss of funds. You are advised to conduct your own due diligence before taking any action.